Can a CA Cite AI-Generated Research in a Tax Opinion?
Last updated:
A chartered accountant may use AI to help research or draft a tax opinion. The more important question is what happens before the opinion is signed: have the legal authorities been verified, has the law been applied to the client’s facts, and has a qualified professional exercised independent judgement?
Consider a typical workflow. An associate uses an AI tool to prepare a note citing two judgments and a circular. The reviewer cannot locate one of the judgments and finds that the circular has been superseded. The right response is not to debate whether the tool is to blame; it is to correct the research before the advice is issued and to strengthen the review process.
AI output should be treated as research assistance, not as legal authority. A signed opinion must be supported by the relevant statute, notification, circular, judgment or other authority, and by the professional’s reasoned application of that material.
1. The professional duty of due diligence
The Chartered Accountants Act, 1949 treats a failure to exercise due diligence, or gross negligence, in the conduct of professional duties as professional misconduct for a chartered accountant in practice. That limb is clause (7) of Part I of the Second Schedule to the Act. Section 22 defines “professional or other misconduct” by reference to the Schedules, and section 21 and the provisions around it set out the disciplinary process.
The standard does not change because an error began in a chatbot, a search engine or a colleague’s note. A professional who adopts a material proposition in an opinion needs an adequate basis for relying on it. How much verification is adequate depends on the nature of the advice, the importance of the issue and the sources available.
2. The ICAI Code of Ethics and AI-assisted work
The revised 13th edition of the ICAI Code of Ethics applies from 1 April 2026. One item in Volume I, on assessment and evaluation of social impact, CSR impact and BRSR-type work, took effect earlier, on 11 December 2025. The Code’s fundamental principles—integrity, objectivity, professional competence and due care, confidentiality and professional behaviour—apply whatever tools are used to perform the work.
In practice, a CA should not be associated with information that is materially false or misleading, and must maintain the competence and care needed to give a reliable service. Those duties do not need an AI-specific rule to bite: an unverified AI citation in a signed opinion engages them directly. Cite the specific principle and provision from the current edition when you rely on the Code.
3. What the Supreme Court has said about fabricated AI authorities
Two 2026 decisions give important context. Neither is a ruling on a CA’s professional disciplinary liability.
Pooja Ramesh Singh v. Jammu and Kashmir Bank Ltd. (2026 INSC 668)
On 2 July 2026, the Supreme Court set aside the NCLT and NCLAT orders in an insolvency matter after finding that the adjudication relied on non-existent, fake or hallucinated material presented as precedent. The Court restored the Section 7 application to the NCLT for decision. It stated that it is misconduct for an advocate to cite such judgments without verification, treated reliance on them by a decision-maker as a serious lapse, and directed the Bar Council of India to constitute a committee to consider guidance and disciplinary norms. The case was not a CA disciplinary matter.
Vijay Ghanshyam Gadiya v. Union of India (2026 INSC 947)
On 2 September 2026, the Supreme Court found that a customs adjudication order imposing a penalty of about ₹425 crore relied on authorities that were non-existent, carried fake citations or did not support the propositions attributed to them. It set aside the High Court’s order and the customs order, and remitted the matter for fresh decision by another officer. The Court did not finally decide the underlying customs liability; it intervened because the order rested on dubious legal material.
These decisions underline the need to verify legal authorities in adjudicatory settings, and they are useful warnings for tax professionals. Whether a CA faces disciplinary consequences in a particular case depends on the Chartered Accountants Act, the ICAI Code and the facts of that case.
4. What counts as independent verification?
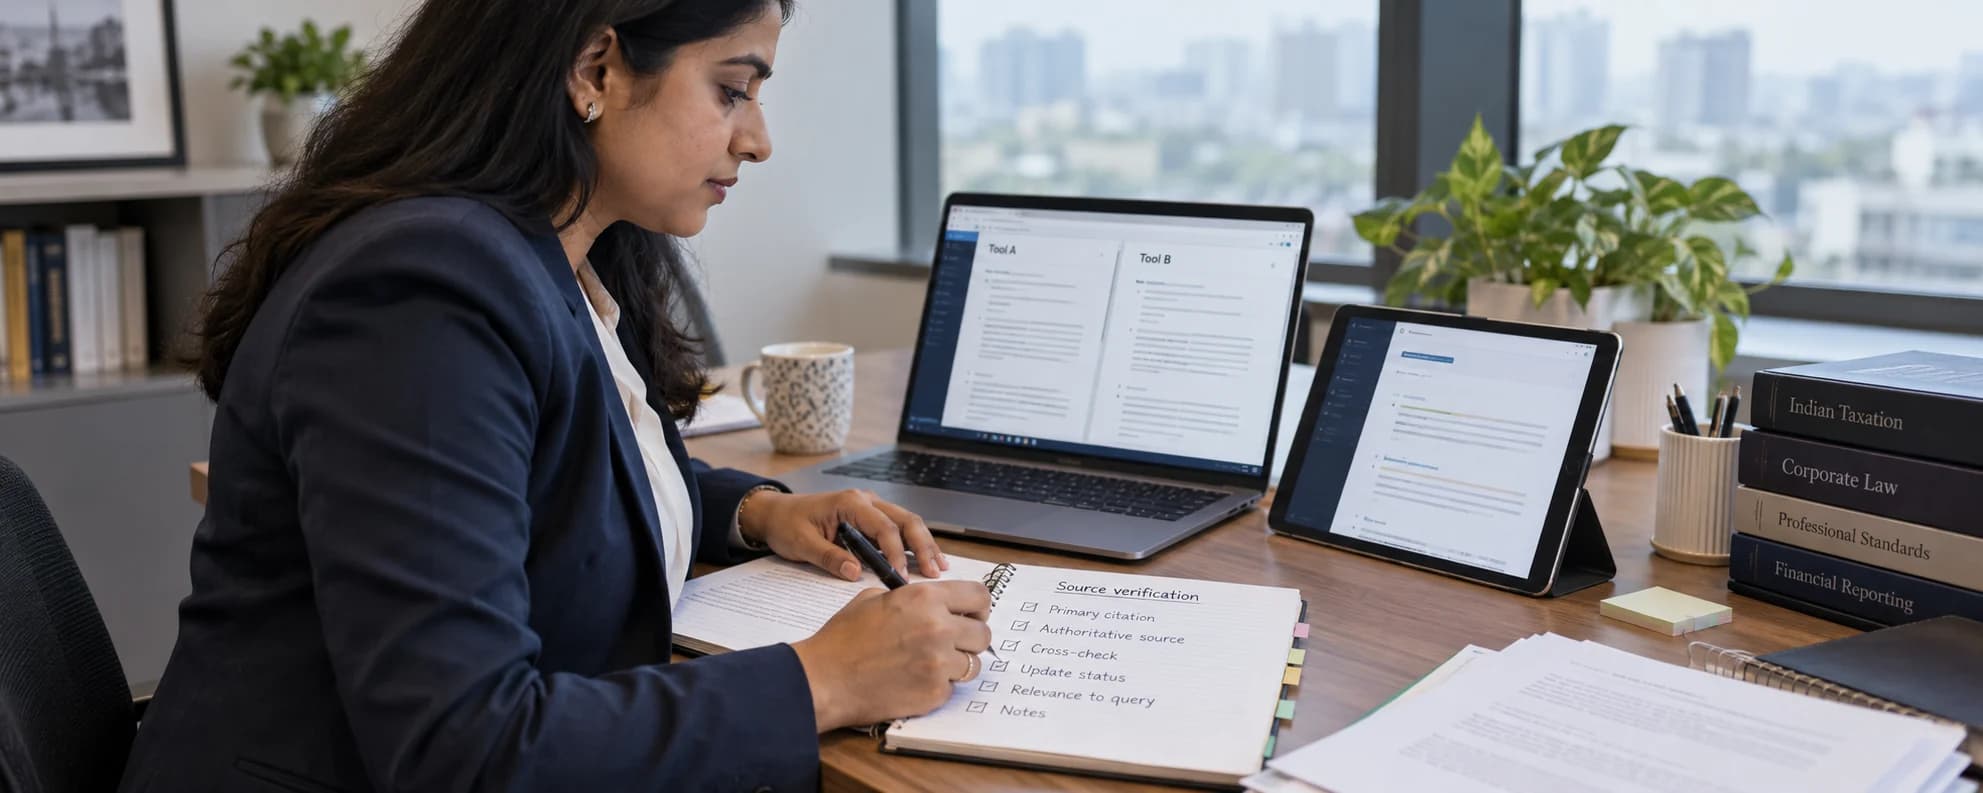
A citation is not verified merely because an AI tool shows a link or because a case name resembles a real one. Verification covers both authenticity and legal relevance.
- Cases: confirm the case name, citation, court or tribunal, date and relevant paragraph in an authoritative reporter or recognised legal database. Open the judgment and read the passage in context.
- Legal proposition: confirm that the passage supports the proposition as stated. Check whether the decision has since been reversed, stayed, overruled, distinguished or read differently.
- Statutes: check the enacted text, amendment history, relevant tax year and commencement provisions. When moving between the Income-tax Act, 1961 and the Income-tax Act, 2025, verify the mapping and any transition rule.
- Rules, circulars and notifications: confirm the issuing authority, number, date, operative text, amendments or withdrawal, and effective date in the official source.
- Application to facts: identify assumptions and missing facts, test exceptions and competing interpretations, and say clearly where the law is unsettled.
5. Build verification into the firm’s workflow
A practical policy need not prohibit AI. It should state how AI may be used and what checks are required before advice is issued. A firm-level process can include:
- Approved uses and tools: distinguish low-risk summarisation or drafting from research that will support a signed opinion or a filing.
- Named responsibility: identify who checks each material authority and who approves the final advice. Reviewers should not assume an earlier stage verified the authorities unless the process records it.
- Research record: keep the source links or copies, the relevant passages, material assumptions and the reviewer’s sign-off in the matter file, consistent with the firm’s confidentiality policy.
- Confidentiality controls: use only approved services for client information, and review retention, training use, access, deletion and security terms before uploading material.
- Training: show staff how to test a citation, spot outdated law, check effective dates and report an answer that cannot be verified.
A product that shows source passages beside its analysis can shorten the checking. It does not remove the need to read the source, exercise professional judgement and take responsibility for the signed opinion. (See also: how to verify a tax answer against primary sources.)
The answer
A CA can use AI as an aid to research and drafting, but should not treat AI-generated text as authority. Every material legal proposition in a signed opinion should rest on a genuine, relevant and current source that has been checked independently. A proportionate, documented verification process protects the client and supports the standard expected of the person who signs the advice.
Related reading
Frequently Asked Questions
1. Can a CA use AI-generated research in a signed tax opinion?
A CA may use AI as an assistive research or drafting tool, but the opinion should rely on verified legal authorities and the professional’s own analysis, not on the AI output as authority. Check the legal text, the citations and the application to the facts before the opinion is issued.
2. Could an unverified AI-generated citation amount to professional misconduct?
It may raise serious concerns where the facts show a failure to exercise due diligence or gross negligence in professional duties, which is clause (7) of Part I of the Second Schedule to the Chartered Accountants Act, 1949. Whether misconduct is established depends on the facts and the disciplinary process. The Supreme Court’s decisions on adjudicatory proceedings do not automatically decide a CA’s case.
3. Does the ICAI Code of Ethics specifically mention AI?
The fundamental principles of the revised 13th edition, effective from 1 April 2026 (with one earlier-effective item in Volume I), apply whether or not a provision uses the term AI. Integrity, objectivity, professional competence and due care, confidentiality and professional behaviour remain relevant when technology is used.
4. What is the minimum check for an AI-generated case citation?
Confirm the case name, citation, court, date and relevant paragraph in an authoritative report or recognised legal database. Read the context, verify the proposition and check subsequent treatment. For statutes and notifications, use the official text and confirm the version and effective date.
5. Should the firm document the verification?
Yes. A documented process can record the research question, the authorities relied on, the verification performed, material caveats and reviewer approval. The method should fit the firm’s risk and workflow while preserving client confidentiality.
Stay in the know with AskSolique.
Occasional insights on tax, regulation, and what’s new at AskSolique. Only when we have something worth sharing.