
SEBI SAST Regulations: The Disclosure Triggers Promoters and Acquirers Still Miss
• By AskSolique.ai Team • Securities Law
A two percent move in a promoter's holding does not feel like an event. It is one. The SEBI SAST regulations attach a two-working-day disclosure obligation to it, and that obligation sits on the person who made the move rather than on the company — which is precisely why it gets missed, because the company secretary often hears about the transaction after the window has closed. This article maps the thresholds that actually matter under the takeover code, the disclosure that survived the 2022 rationalisation and the one that did not, the encumbrance obligation almost nobody diaries, and why automated filings do not discharge anyone's duty. It is the kind of cross-reading that defines regulatory work for company secretaries.
Three thresholds, three different consequences
The most common error in applying the SEBI SAST regulations is treating them as one rule with one number. It is not. Three distinct thresholds do three different things, and crossing one says nothing about the others.
| Threshold | What it triggers | Provision |
|---|---|---|
| Acquiring 25% or more of voting rights | Mandatory open offer | Reg. 3(1) |
| Holding 25% or more and acquiring a further 5% in a financial year | Mandatory open offer (creeping acquisition limit) | Reg. 3(2) |
| Acquiring control, irrespective of shareholding | Mandatory open offer | Reg. 4 |
| Acquiring 5% or more of shares or voting rights | Disclosure only | Reg. 29(1) |
| Every change of 2% or more once above 5% | Disclosure only | Reg. 29(2) |
The first three reshape a transaction. The last two are filings. Confusing them cuts both ways: panic about an open offer on a 6% purchase, or a casual crossing of 5% with nothing filed at all.
Regulation 29(1) and 29(2): the two-working-day disclosure
An acquirer — alone or with persons acting in concert — who acquires shares or voting rights aggregating to 5% or more must disclose the aggregate shareholding and voting rights to the target company and to every stock exchange where the shares are listed, within two working days of the acquisition or of receiving intimation of allotment. For companies on the Innovators Growth Platform the threshold is 10%.
Once above that line, Regulation 29(2) takes over. Any change of 2% or more in shareholding or voting rights must be disclosed on the same two-working-day clock. Two points here are routinely misread. It applies to decreases as well as increases, including a disposal that takes the holder below 5%. And the 2% is measured against the total share capital of the target, not against the holder's own stake - a common and expensive slip.
The disclosure runs to the target company as well as the exchanges, and the target's compliance officer is often the person who notices the omission - reason enough to ask promoters to copy the company on filings routinely.
The annual disclosure that no longer exists
Here is where older checklists mislead. Regulation 30 of the takeover code once required annual disclosures of shareholding by promoters and by holders above 25%. It was omitted entirely, with effect from 1 April 2022, on the reasoning that the same information was already reaching the market through shareholding patterns and system-driven filings.
Yet it still appears on compliance calendars in circulation, and teams occasionally chase promoters for a filing that has not been required for four years. The cost is not a penalty but credibility, and time spent on work that no longer exists. If your calendar carries an annual shareholding disclosure line, delete it.
What survived is narrower and more specific, and it is the part people forget.
Regulation 31: encumbrance, and the declaration nobody diaries
A promoter, or any person acting in concert with a promoter, must disclose the creation, invocation or release of an encumbrance over shares of the target company within seven working days. Encumbrance is read widely under the takeover code — it is not limited to a registered pledge, and non-disposal undertakings and similar arrangements have been brought within it.
Separately, promoters must make an annual declaration, within seven working days of the end of the financial year, that they have not made any encumbrance not already disclosed. This obligation arises whether or not anything happened during the year, which is exactly why it slips: there is no transaction to prompt it. It belongs in the compliance calendar as a fixed-date item alongside the other April filings, with the declaration and its covering letter drafted from the same mapped position each year rather than rebuilt from memory.
Encumbrance questions also surface who really stands behind a shareholding, which runs into separate reporting on significant beneficial ownership- a different regime, a different test, and no assumption that satisfying one satisfies the other.
System-driven disclosures do not discharge the obligation
Depositories and exchanges now generate certain disclosures automatically from demat data, and that automation was part of the rationale for trimming the manual filing set in 2022 as SEBI regulations shifted toward depository-generated reporting. It is also widely misunderstood.
Automated capture works for transactions passing through the depository system. It does not cover everything - off-market arrangements, transactions outside the depository route and several encumbrance structures fall outside it. The acquirer's own obligation under the SEBI SAST regulations is not extinguished by a system-generated filing, and relying on automation to catch a transaction it was never designed to see is a real risk, not a theoretical one.
The practical test is simple: if you cannot point to the specific filing that discharged the obligation, assume it has not been. Checking that against the current provision, the relevant SEBI master circular and the exchange's filing page takes minutes when the provision and its circulars can be read together, and far longer when they cannot.
Regulation 29 of SEBI LODR is not this Regulation 29
Worth naming plainly, because it confuses cross-functional teams. Two separate SEBI regulations carry a Regulation 29. Under the takeover code it is an acquirer's disclosure of a shareholding change. The listing-side provision is the company's prior intimation of a board meeting. Same number, different rulebook, different obligated person, different clock - and the formats sit in different SEBI master circulars too.
A related trap arises with foreign acquirers, where exchange control conditions carry their own reporting and pricing requirements - the distinction between FDI and FPI routes often determines what else is due alongside the SAST filing.
The answer, in one line
Under the SEBI SAST regulations, crossing 5% and every subsequent 2% change require disclosure to the target and the exchanges within two working days; encumbrance events require disclosure within seven working days plus an annual promoter declaration; the open offer thresholds of 25%, creeping 5% and acquisition of control are separate questions entirely; and the old annual shareholding disclosure under Regulation 30 has not existed since 1 April 2022.
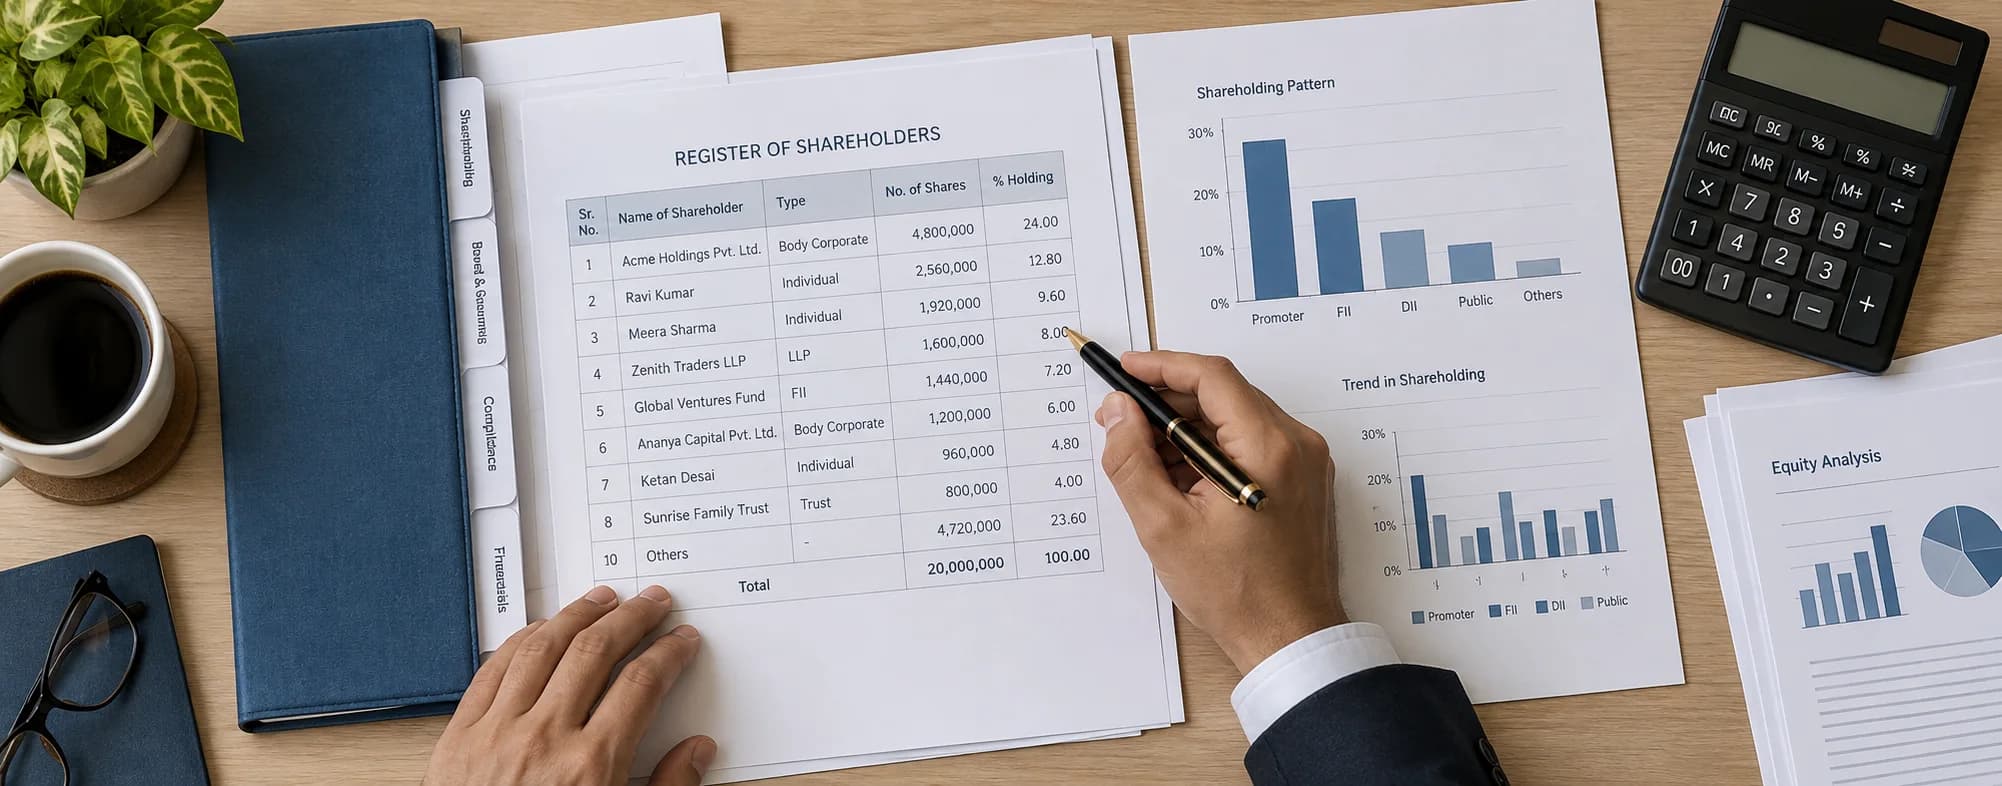
Take the promoter and significant-shareholder register for every listed client, map each holding against these thresholds, and confirm which filings were actually made rather than assumed automated. Most gaps surface in that one exercise.
References
Frequently Asked Questions
Do persons acting in concert disclose individually or jointly?
The thresholds are computed on the aggregate holding of the acquirer together with persons acting in concert, so the trigger is assessed collectively even where individual holdings are small. The filing itself identifies the acquirer and each PAC with their respective holdings. A frequent error is testing each person separately against 5% and concluding nothing is due, when the combined holding crossed the line weeks earlier.
Does an inter-se transfer between promoters need a SAST disclosure?
Yes, if it crosses a threshold. Exemption from the open offer obligation for qualifying inter-se transfers between promoters is a separate question from the disclosure obligation, and being exempt from one does not remove the other. Exempt transfers also carry their own reporting requirement to the exchanges. Treat the open offer analysis and the disclosure analysis as two independent checks on the same transaction.
Does a rights issue or bonus issue trigger Regulation 29(2)?
It can. The test is the change in the holder's percentage of total voting rights, so a shareholder who subscribes to more than their entitlement in a rights issue, or whose percentage moves by 2% or more because others did not subscribe, has a disclosable change. A proportionate bonus issue generally leaves percentages unchanged. Compute the before-and-after percentage rather than assuming corporate actions are neutral.
What counts as an encumbrance beyond a pledge?
The definition is deliberately wide and has been read to cover arrangements that restrict a promoter's ability to deal freely with shares, including non-disposal undertakings and certain covenants in financing documents, not only registered pledges. Because the drafting is broad and has been extended over time, treat any lender or investor arrangement touching promoter shares as potentially disclosable and check the current definition rather than working from an older understanding.
Is the target company obliged to do anything when it receives a SAST disclosure?
The filing obligation rests on the acquirer, not the company. That said, the target's compliance team is usually the first to notice an inconsistency between a disclosure received and the shareholding pattern being prepared, and a mismatch is worth raising immediately rather than at quarter end. Many companies now maintain a promoter and significant-shareholder register for exactly this reconciliation, though no provision requires it.
Recent Blog Posts
See All Posts
SEBI SCORES: The 21-Day Clock a Listed Company Cannot Miss
AskSolique.ai Team •
What Is FEMA? Meaning, Purpose, Key Provisions & Compliance in India
AskSolique.ai Team •