Why General AI Chatbots Can Get Indian Tax Law Wrong
Last updated:
An AI answer can be polished, confident and wrong. In Indian tax practice that matters: a missed amendment, a misread proviso or a citation that does not support the stated proposition can undermine an otherwise careful piece of work.
Imagine an associate preparing a tax note with the help of a chatbot. The draft refers to a statutory section and two court decisions. Before the note reaches the client, a reviewer finds that one reference is outdated and the other cannot be located. The example is hypothetical, but the failure pattern is real: fluent language can conceal weak or unverified research.
General-purpose AI is not useless for tax work. It can help frame questions, organise facts and produce a first draft. The problem starts when a plausible answer is treated as an authoritative statement of current law.
1. Language fluency is not the same as legal research
Large language models generate responses from patterns learned during training and, depending on the product, from information retrieved through search or connected sources. Products differ in their training data, legal databases and live-retrieval features. A model may explain a familiar rule well yet struggle with an exception, a conflicting judgment or a provision that has changed.
Claims about a model’s legal knowledge should therefore be tested against the specific version and configuration in use. A response that sounds like a tax opinion is not evidence that the statute or judgment was actually checked.
2. Legislative change makes old knowledge risky
The Income-tax Act, 2025 came into force on 1 April 2026 and reorganised the structure and numbering of many provisions. A researcher who keeps using a familiar 1961 Act reference without checking the relevant tax year may cite the wrong provision or overlook a transition rule.
For example, section 80C of the Income-tax Act, 1961 broadly corresponds to section 123 of the 2025 Act. The life-insurance exemption formerly in section 10(10D) is now set out in section 11 read with Schedule II, Table item 2. These examples show why mappings must be verified; they do not replace checking the conditions and transitional provisions that apply to a particular case.
The same caution applies to Finance Act amendments, rules, CBDT and CBIC circulars, notifications and judicial interpretations. A section number may be valid yet irrelevant to the tax year, transaction or question being analysed.
3. Access to current sources must be tested
Some AI products search the web or retrieve from a curated legal corpus. Others answer mainly from model knowledge. Even with live search, a system can retrieve an outdated page, miss a corrigendum or summarise a rule without accounting for its effective date.
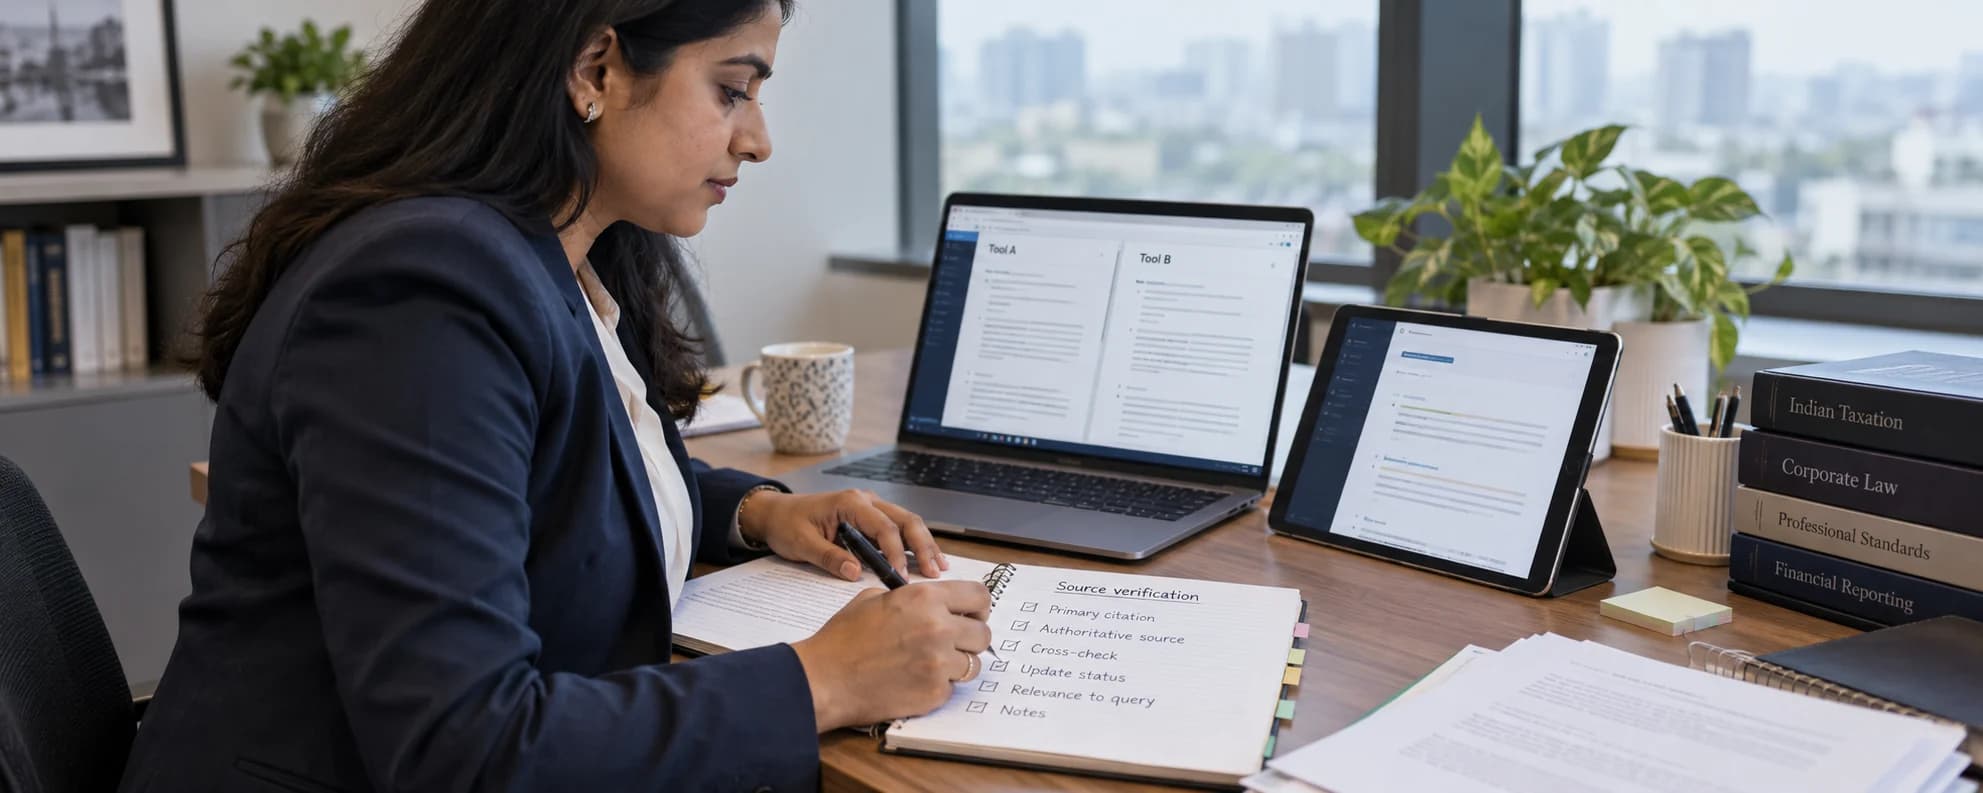
A useful test is to give the tool a recent, verifiable notification and ask it to identify the issuing authority, date, operative change and effective date. Then open the official source and compare. Ask the vendor how updates are ingested and how corrections are handled; do not rely on a broad claim that the product is “up to date.”
4. Citations can look real without supporting the answer
Checking a citation means more than confirming that a case name or neutral citation exists. The cited judgment must be the right decision, the quoted paragraph must appear in it, and the judgment must actually support the proposition attributed to it. A real case can be misquoted or used for a point it never decided.
The Buckeye Trust matter before the Bengaluru Bench of the Income Tax Appellate Tribunal is a cautionary example. The Tribunal recalled its order of 30 December 2024 on 7 January 2025, citing “certain inadvertent errors”; the recall order itself does not mention AI. The AI concern came from press reports pointing to apparently non-existent authorities in the original order, and from the assessee’s writ petition before the Karnataka High Court, which said the order appeared to have been driven by artificial intelligence. No tribunal finding identifies an AI tool as the source of the errors, so the episode is best read as a warning rather than as proof about any product.
The Supreme Court has since dealt squarely with fabricated AI-generated precedents. In Pooja Ramesh Singh v. Jammu and Kashmir Bank Ltd. (2026 INSC 668, decided 2 July 2026), the Court set aside the NCLT and NCLAT orders in an insolvency matter after they relied on non-existent or misattributed authorities, restored the Section 7 application to the NCLT, and directed the Bar Council of India to constitute a committee on safeguards and disciplinary norms. In Vijay Ghanshyam Gadiya v. Union of India (2026 INSC 947, decided 2 September 2026), the Court set aside a customs penalty of about ₹425 crore and the High Court order upholding it, because the adjudicating officer had relied on case laws that were non-existent, carried fake citations or did not support the propositions attributed to them. The matter went back for fresh adjudication by a different officer.
Both rulings arose in adjudicatory proceedings, not in a CA disciplinary matter, and they should not be read as rulings on a chartered accountant’s professional liability. Their lesson for tax researchers is narrower but important: legal authorities must be independently verified before anyone relies on them.
5. What does a reliable verification workflow look like?
Use AI to speed up research, not to take the researcher out of it. Before a tax note, appeal submission or opinion is finalised:
- Open every cited statute, rule, notification and circular in an official source. Confirm the exact text and effective date.
- Check every case citation in an authoritative reporter or recognised legal database. Read the relevant paragraphs rather than relying on a generated summary.
- Confirm that the decision has not been reversed, stayed, overruled or materially distinguished, and note the level of the court or tribunal.
- Apply the authority to the client’s facts independently. Flag assumptions, missing facts and competing interpretations.
- Record who verified the authorities and who reviewed the conclusion before the document is issued.
6. What the benchmark evidence does—and does not—say
The Taxmann.AI–IIT Kharagpur LE-BTL study reports material differences between models and subject areas. Its published methodology describes more than 100 expert-validated questions spanning direct taxes, GST, FEMA, accounting standards and judicial precedents. The highest direct-tax score reported was 72.84%, and the study noted that models were weaker at applying law and justifying conclusions than at identifying issues and rules.
This is a useful warning about the limits of the models tested, not a permanent accuracy ceiling for every AI product. The models, prompts, questions and scoring approach all affect the results, and model capabilities keep changing.
The practical takeaway
Judge an AI answer by the authority behind it, the quality of its reasoning and its fit with the applicable law and facts—not by its tone. Curated legal sources and pinpoint citations can make checking faster, but they do not remove the need for independent verification and professional judgement.
Related reading
Frequently Asked Questions
1. Why can AI give an incorrect section number for Indian tax law?
A language model may rely on earlier material, confuse similar provisions or generate a plausible-looking reference without actually checking the statute. The risk depends on the model, tools and sources available in that session. Always verify the provision and its effective date against the applicable Act and rules.
2. Did the Income-tax Act, 2025 change section numbers?
Yes. The Income-tax Act, 2025 took effect from 1 April 2026 and reorganised many provisions. For example, section 80C of the 1961 Act broadly maps to section 123 of the 2025 Act; the former section 10(10D) exemption is now addressed in section 11 read with Schedule II, Table item 2. Check the official Act and mapping navigator for the provision relevant to your facts.
3. What does the Buckeye Trust incident show?
The ITAT Bengaluru recalled its 30 December 2024 order on 7 January 2025, citing inadvertent errors. Press reports pointed to apparently non-existent authorities in the original order, and the assessee’s writ petition suggested AI involvement. The recall order did not name an AI tool, so any attribution to a particular product is an allegation, not a tribunal finding.
4. Can AI browse the latest tax notifications?
Some products can search the web or retrieve documents, while others rely more on built-in model knowledge. Access to search does not guarantee that the right official notification was found or correctly interpreted. Verify the date, issuing authority, amendments and effective date in the official source.
5. Can a tax professional use AI safely?
AI can help organise research, summarise documents and prepare a first draft. Before relying on its legal conclusions, the professional should independently verify the authorities, test the reasoning against the client facts and document the review.
Stay in the know with AskSolique.
Occasional insights on tax, regulation, and what’s new at AskSolique. Only when we have something worth sharing.